What is Life Insurance?

Make sure your family can stay in your home

We understand that in many cases your life savings has gone into the purchase of your new home. Keeping that roof over your family’s head is understandably of utmost importance.

Could they still afford to live there should the worst happen to you? Life insurance undoubtedly helps with this. Whilst we cannot replace you, we can replace the income that runs your household. Being a life insurance broker plays an important part of the service we provide.

Life insurance is designed to give you peace of mind that know if you were to pass away your family would be looked after and not left in any financial hardship and risk losing the home you’ve worked so hard to get. It provides a cash lump sum so that the mortgage can be taken care of, so your family doesn’t have to.

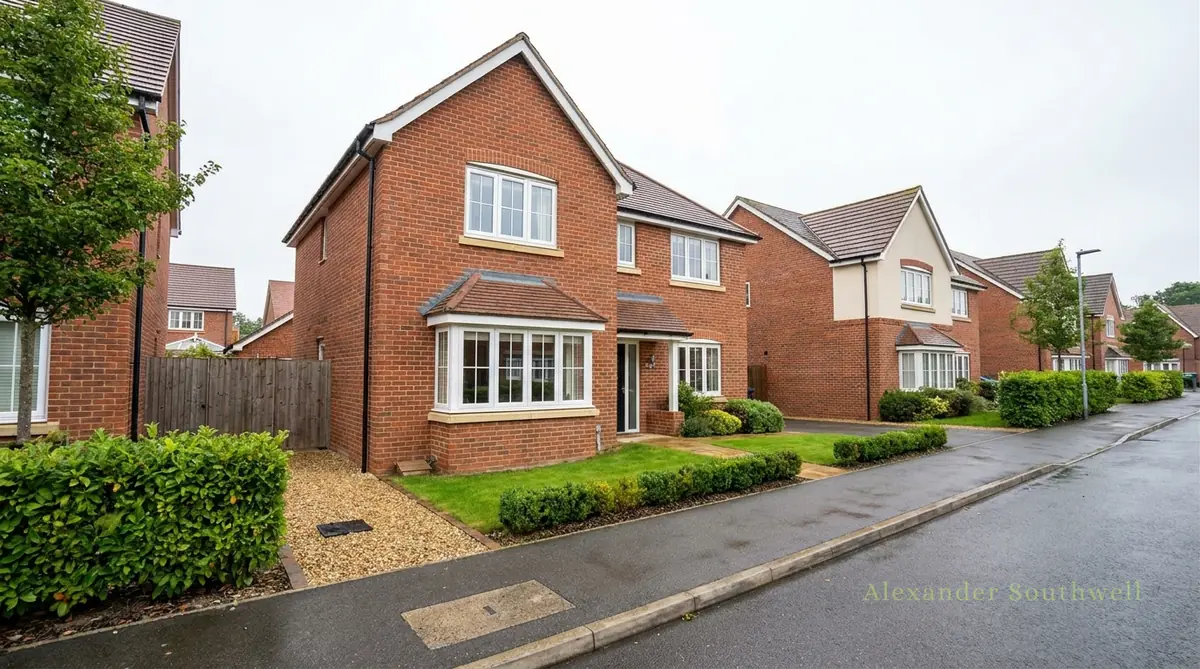
Family protected by life insurance in Southampton and HampshireFamily home protected by life insurance arranged through our advisers

Do You Need Life Insurance?

Life insurance provides a lump sum or regular income to your family if you pass away during the policy term. While it is not a legal requirement, most mortgage lenders will recommend it as a way of ensuring your loved ones can continue to meet mortgage repayments should the worst happen. It is one of the most straightforward and cost-effective ways to protect the people who depend on you financially.

For families with children or other dependants, life insurance can be particularly valuable. The payout from a life insurance policy can cover an outstanding mortgage balance, household bills, childcare costs and everyday living expenses, providing your family with financial security at an incredibly difficult time.

We compare life insurance from a wide panel of insurers to find the right level of cover at a fair premium. We advise on decreasing life insurance, level term life insurance and family income benefit. You do not pay us a fee for protection advice, and we help clients in Romsey, Southampton and across the UK.
Related protection advice:

Many of our clients combine life insurance with other forms of cover for complete peace of mind. Find out more about critical illness cover insurance, income protection insurance and buildings and contents insurance, or visit our main mortgage protection insurance page.

It is not compulsory to have life insurance in place to get a mortgage, but it is highly advisable. A mortgage is most likely the biggest debt you will leave behind and it is possible to get your total mortgage loan covered cheaply by a life insurance policy, here is further information on the policies to consider:

What term should my life insurance be over?

Policy Term

The term of the policy is specified at the outset of the policy starting. In simple terms, it means how long you are protecting yourself for example 1 to 50 years. Often the term is decided by the following points:

Mortgage term: If your sole purpose is to protect the mortgage then usually the life insurance will coincide with your mortgage term. So, however many years you decide to do the mortgage over, the life insurance will coincide with this.

Dependents:
Taking the policy to an age whereby the children are financially independent. For example, 18 once they have finished school or 23 after university.

Retirement age:
Make sure that your income is protected should the worse happen therefore by taking the policy to retirement age when your income is then your pension.

Whole of life:  
Is what it says on the tin. Ideal for someone who is looking to make sure they have provisions in place for funeral costs, inheritance or inheritance tax liability .

Life insurance adviser at Alexander Southwell Mortgage Services in Southampton

Deciding which life insurance cover type is suitable for you and your family can seem challenging however we are here to help and guide you into making the right decision. Whether you simply want to protect the mortgage, help to maintain the same standard of living or simply cover funeral costs there are 3 options for you to choose from:

Your options

The Three Types Of Life Insurance For Mortgages

Decreasing term life insurance

The payout reduces over the term, roughly in line with what you owe on a repayment mortgage. Because the cover decreases, it is typically cheaper than level cover, and it is the most common way to protect a repayment mortgage.

Level term life insurance

The same amount is paid whenever you die during the term. It suits an interest only mortgage, where the outstanding balance stays the same, or families who want money left over for living costs and other debts once the mortgage is cleared.

Family income benefit

Instead of a lump sum, your family receives a monthly income for the rest of the term. It works well as income replacement while children are growing up, and it is usually one of the cheaper types of policy.

Good to know:Life insurance policies can be written in trust at no cost to you. Placing the policy in trust means the pay-out sits outside your estate and bypasses the probate process, so your family receives the money more quickly. Our advisers can explain how trusts work and set this up as part of your application.

Add-Ons

Additional Benefits to consider when purchasing Life Insurance

Terminal Illness benefit: Included within the policies is terminal illness benefit. In the awful event that you are given less than 12 months to live you will receive the pay-out whilst you are still alive. This can be used to help you and your family during this extremely difficult time so that you have no financial worries or stress.

Accidental death cover: many insurers give you free accidental death cover while they assess your application, so you have some protection from day one.

House purchase cover: This gives you free life cover before your policy starts from when you exchange contracts to when your house purchase is complete

Fracture cover: Fracture cover pays you a lump sum if you suffer one of the specified fractures during any 12-month period. Most insurance companies will pay one successful claim each policy year.

How it works

Life Insurance For Mortgages Explained

Life insurance for mortgages is about making sure the people you live with can stay in the home if you die. Here are the questions we go through with clients before recommending a policy.

How much life insurance do you need?

At the very least, enough to pay off the mortgage. Many families add a cover amount for other debts, childcare and a year or two of household bills. If you have a mortgage of £220,000 and two children, the right figure is often higher than the mortgage balance alone.

Joint policy or two single policies?

A joint policy pays out once, on the first death, and then ends, leaving the surviving partner without cover. Two single policies cost a little more but can pay out twice, which is worth thinking about if you both earn or have children.

Adding critical illness cover

You can add critical illness cover to a life insurance policy, so it also pays out if you are diagnosed with a serious illness such as cancer, a heart attack or a stroke. It costs more, and a combined policy only pays once. Read more on our critical illness cover page .

Guaranteed premiums

Most mortgage life insurance policies have guaranteed premiums, so the monthly premium stays the same for the whole term. Reviewable premiums start lower but can go up later, which makes them harder to budget for.

Health issues and pre existing conditions

Insurers ask about your health, family history and lifestyle. Pre existing conditions, such as high blood pressure or diabetes, can mean a higher premium or an exclusion, but cover is often still available. Telling the insurer everything is what makes sure a claim is paid.

Life insurance claims

When someone dies, the family or the trustees contact the insurer with the death certificate and policy details. If the policy is written in trust, the payout can usually be made within a few weeks rather than waiting for probate.

Do you need life insurance for a mortgage?

It is not compulsory, and no lender can make you take a particular policy. But if anyone relies on your income to pay the mortgage, mortgage life insurance is usually the first piece of protection we suggest, often alongside income protection . Our mortgage protection insurance page explains how the different policies fit together.

You do not pay us a fee for protection advice. If you decide to take out a policy, the insurer pays us commission. We compare policies from across the whole of the market and explain what each one does and does not cover before you decide.

More questions

Is life insurance for mortgages the same as mortgage protection?

Mortgage life insurance is one type of mortgage protection. Mortgage protection is the wider term, and it also covers income protection, critical illness cover and mortgage payment protection insurance.

Does life insurance pay off my mortgage automatically?

No. The payout goes to your estate, your partner or the trustees, who then use it to clear the mortgage. Writing the policy in trust speeds this up.

What happens to my life insurance if I remortgage?

Your policy carries on as long as you keep paying. If you borrow more or extend your term, check the cover still matches the new mortgage.

Can I get life insurance with a health condition?

Usually, yes. Many conditions mean a higher premium or an exclusion rather than a refusal. Comparing insurers matters, because they view the same condition differently.