Being prepared with the right paperwork
Documents You’ll Need
Buying in Salisbury means juggling viewings, solicitors and a chain, often with a cathedral city price tag. Our job is to take the mortgage side off your plate. We look at your income, deposit and plans, compare lenders across the market, then handle the application through to completion. Most of our Salisbury clients never need to visit us, because everything works by phone, video and email.


Alexander Southwell Mortgage Services Ltd offer a comprehensive range of mortgage products from across the market. We offer both first and second charge mortgages, but not deals that you can only obtain by going direct to a lender.
We work closely with Salisbury estate agents, solicitors, and surveyors to ensure your mortgage completes as smoothly as possible.

Fee free on over 90% of cases. Mortgages under £100,000 carry a £299 fee, and complex or adverse credit cases up to £995. Remortgages are always fee free.
Over 90% of our cases are fee free because the lender pays us on completion. Mortgages under £100,000 carry a £299 fee and complex cases up to £995, always agreed in writing before we start.
Covering Salisbury, Harnham, Laverstock, Old Sarum, Wilton, Amesbury, Downton and the villages of south Wiltshire.
First time buyers, home movers, remortgages, buy to let (including portfolio landlords).
Speak to a qualified broker by phone or video, often on the same day you get in touch.
We help people across Salisbury, Wilton, Amesbury and the surrounding villages with first homes, moves, remortgages and buy to let. You keep the same broker from the first call to the day you get the keys, and we stay in touch when your deal comes up for renewal.

From your initial consultation to when your mortgage completes we manage the whole process for you. We coordinate with estate agents and solicitors where necessary to keep everyone moving towards your completion date.
Call or enquire online and one of our Salisbury mortgage advisers will get back to you quickly to discuss your needs.
Your adviser will compare mortgage products across suitable lenders and prepare a tailored recommendation. You’ll receive an Illustration (ESIS) showing the interest rate, fees and total cost over the mortgage term so you can make an informed decision.
We'll secure a Decision in Principle (DIP) so you can make offers on Salisbury properties with confidence.
We’ll handle the paperwork, submit your documents to the lender, liaise on your behalf and arrange the valuation or survey. You won’t need to chase. We do that for you.
We’ll track your case through underwriting, chase solicitors and other parties if needed and keep you updated through to exchange and completion. Once you’ve got your keys we’ll diarise a review before any fixed rate ends so you’re never left on an expensive standard variable rate.
Being prepared with the right paperwork
Documents You’ll Need
Salisbury sits in a sweet spot: a small cathedral city with its own hospital and big defence employers, surrounded by countryside, with direct trains to London. That mix keeps demand steady from families, forces households, commuters and people moving out of the South East.
Homes in Salisbury sold for an average of £341,893 over the last year on Rightmove's sold price data, around 2% lower than the year before. Across the Wiltshire Council area the official average was £329,000 in July 2026, up 2.6%.
Terraced homes in the city average around £307,000, semi detached homes about £360,000 and detached homes closer to £503,000. Wiltshire's first time buyers paid an average of £263,000.
Staff at Salisbury District Hospital, scientists and engineers at Porton Down and Boscombe Down, Army families from the garrisons on Salisbury Plain, London commuters and people downsizing from elsewhere in the South.
The fastest trains reach London Waterloo in about 1 hour 20 minutes, with direct services to Southampton, Bristol, Bath and Cardiff. The A36, A30 and A338 meet here, and the A303 runs just to the north.

First time buyers often start with a Victorian terrace in Fisherton, a flat near the centre or a newer home around Old Sarum. With Wiltshire's first time buyer average at £263,000, a 5% deposit is about £13,150. We work out what you could borrow, which lenders suit your income and whether any schemes help.
If your fixed rate ends in the next six months, we compare a product transfer with your current lender against the whole market and recommend whichever costs less overall. Remortgages are always fee free with us, including releasing equity for home improvements.
Salisbury has steady rental demand from hospital staff, defence contractors and service personnel. Lenders usually want the rent to cover 125 to 145% of the mortgage payment at a stressed rate, so we check the numbers on a property before you commit, in your own name or through a limited company.
New build homes go up around Old Sarum and in nearby towns such as Amesbury. We know how developer incentives, reservation deadlines and the six month offer window work, and we talk to the sales team so exchange happens on time.
These are the figures we use when we sit down with a Salisbury buyer for the first time. They give a feel for the deposit and income you might need before you start booking viewings.
Take a couple buying a two bed terrace in Fisherton for £307,000, close to the city's average for that type of home. With a 10% deposit of £30,700 they would borrow £276,300. Many lenders cap borrowing at around 4.5 times income, which points to a joint income of about £61,400, though some lenders go further for higher earners or on certain products. Over 30 years at an illustrative 4.5% rate, the monthly payment would be about £1,400. That is an example, not a quote, and your own figures will depend on your credit file, outgoings and the deal available on the day.
Sources: Rightmove sold prices for Salisbury; UK House Price Index (HM Land Registry and ONS), July 2026; ONS Price Index of Private Rents, August 2026; Trainline.
Every part of the city has its own feel, and lenders treat some property types differently. These are the areas our clients ask about most.
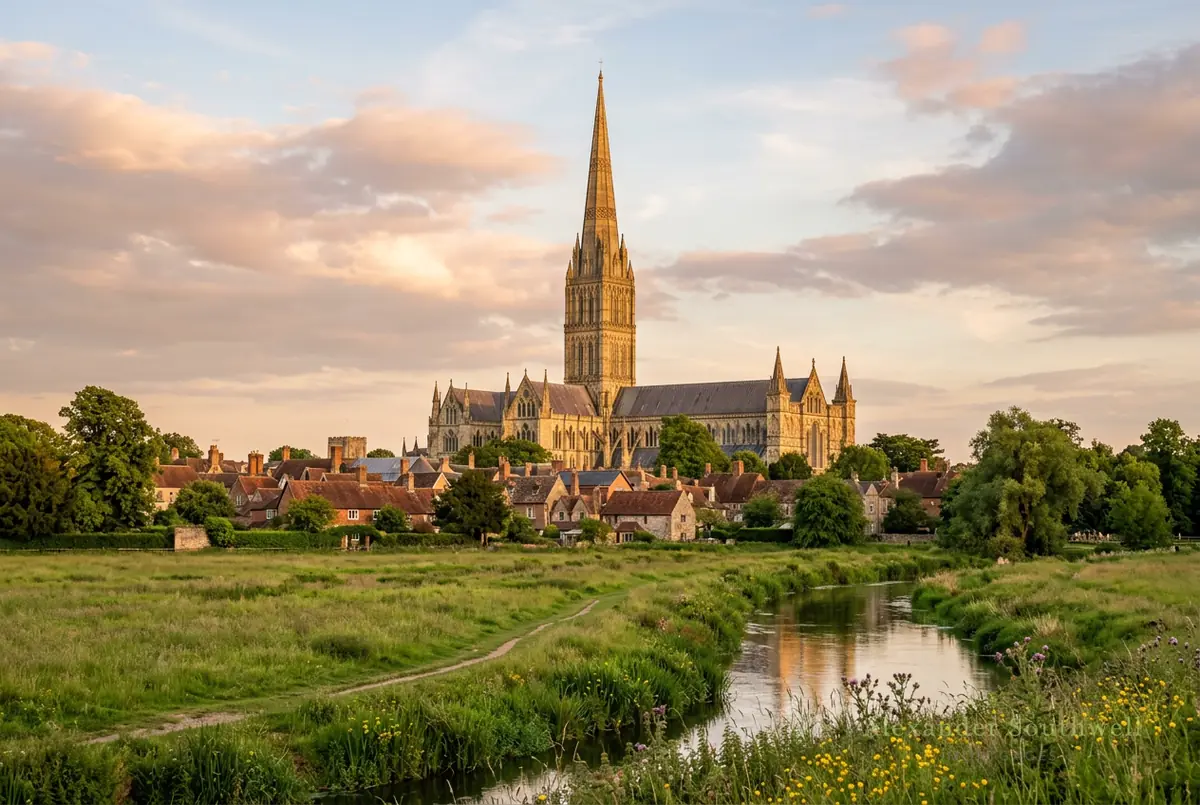
South of the river, with family homes, views back to the cathedral spire and the water meadows on the doorstep. A popular move for growing families.
Victorian terraces and flats close to the station and the shops. Good for first time buyers and commuters who want to walk to the train.
Newer estates on the north eastern edge of the city, close to schools and the A30. Plenty of three and four bedroom houses.
A newer area north of the city by the old airfield, with a lot of new build stock. Worth checking how the developer's timescales fit your mortgage offer.
A small town a few miles west with its own character, period cottages and a slightly lower price point than the city centre.
On the A303 near Stonehenge, popular with Army families from Bulford, Larkhill and Tidworth, with plenty of newer homes.
Most mortgages here are straightforward. A few local quirks are worth knowing about before you make an offer, because they change which lenders will help.
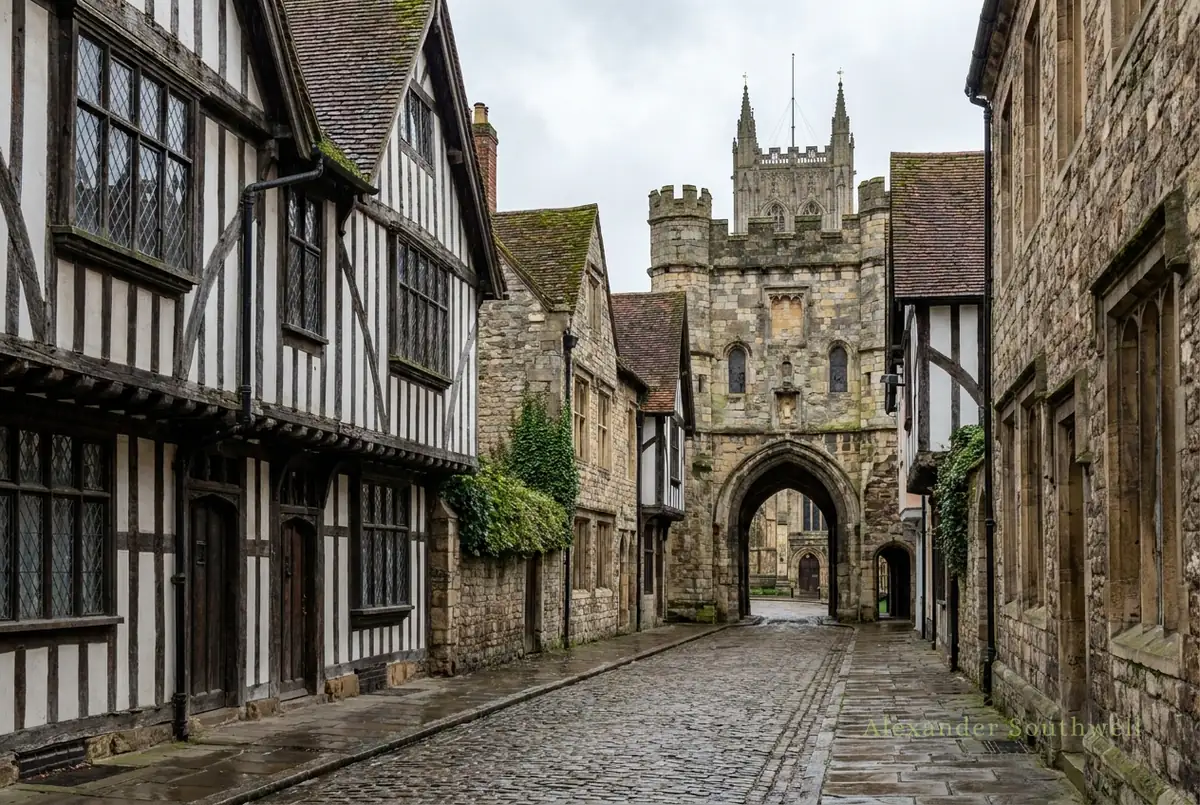
The Cathedral Close and much of the old city are conservation areas with plenty of listed buildings. Some lenders are cautious with listed, timber framed or non standard homes, so we pick lenders that are comfortable with them from the start.
Thatch is common in the villages around the city. Insurers have been leaving that market, and average premiums rose from £598 in 2022 to £2,404 in 2026. Lenders need cover in place before completion, so get a quote before you exchange.
The Avon, Nadder and Bourne meet in the city. The £27 million Salisbury River Park scheme protects more than 350 homes and businesses, but it is still worth checking the flood report and insurance on any riverside home.
Service personnel can borrow up to 50% of salary, capped at £25,000, interest free, towards a home. We check how your lender treats it and line the money up with your exchange date.
From working out what you could borrow to getting the mortgage offer, with every step of the mortgage process explained in plain English.
Porting your current deal, borrowing more or starting again with a new lender. We work out which costs less once early repayment charges are counted.
We start looking up to six months before your current deal ends and compare a product transfer with the rest of the market. Remortgages are always fee free with us.
For landlords buying or remortgaging, in your own name or through a limited company. Lenders look at the rental income as well as your own income.
Sole traders, company directors and contractors. We know which lenders will use your latest year of figures and which want an average of two.
Missed payments, defaults or a CCJ do not always rule you out. We start by going through your credit file with you before anything is applied for.
Tight exchange deadlines, developer incentives and the extra checks lenders run on brand new homes. I spent four years as a specialist new build broker.
Life cover, critical illness cover and income protection, so the mortgage still gets paid if life takes a turn. Our protection advice is whole of market.
Written by Jamie Alexander, CeMAP qualified mortgage adviser and director of AS Mortgages
Jamie has 15 years in mortgages and founded the firm in 2019. The team has submitted over 2,500 mortgage applications and has well over 20 years of combined experience. Alexander Southwell Mortgage Services is authorised and regulated by the Financial Conduct Authority, firm reference 1011890. More about Jamie .
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
.webp)
Yes. We are based in Romsey, about half an hour from Salisbury, and help clients across the city and south Wiltshire. Over 90% of our cases are fee free because the lender pays us. Mortgages under £100,000 carry a £299 fee and complex cases up to £995, and remortgages are always fee free.
Many lenders will consider 5%, although 10% opens up more choice and usually better rates. On a £307,000 terrace, that is about £15,350 at 5% or £30,700 at 10%, plus solicitor fees, a survey and any stamp duty.
Yes. Most lenders want two years of accounts or SA302s, and some will use one year in the right circumstances. Contractors working at Porton Down or Boscombe Down can often be assessed on their day rate instead.
It is not a legal requirement, but most Salisbury estate agents ask for one before they put your offer forward. We can usually arrange one the same day, and it shows the seller you are ready to proceed.
No. Our office is at NIX Business Centre, 2 Park Court, Romsey SO51 9DH, about half an hour away. Most Salisbury clients work with us by phone and video, but you are welcome to come in if you prefer to meet face to face.
Yes. Eligible service personnel can borrow up to 50% of their salary, capped at £25,000, interest free. It is often used as the deposit. We check the lender is happy with it and that the timings line up with your purchase.
Not always, but fewer lenders will look at it and the survey matters more. Thatched homes also cost more to insure, and lenders need buildings insurance in place before completion, so get a quote early.
From a full application, an offer often arrives in two to four weeks, depending on the lender and the valuation. Having your payslips, bank statements and ID ready speeds it up.
We get in touch around six months before your current deal ends, compare the market with your lender's own offer and lock in a new rate, so you do not drift onto the standard variable rate.