Being prepared with the right paperwork
Documents You’ll Need
Finding a mortgage can be stressful when you are juggling property searches, solicitors and a chain. Southampton is a big, varied city, with Victorian terraces in Shirley, student houses in Portswood, waterside flats in Ocean Village and family homes in Bassett, and lenders look at each of those differently. A good local mortgage broker knows which lenders suit which home, so you get the right mortgage deal without applying blind.


Alexander Southwell Mortgage Services Ltd offer a comprehensive range of mortgage products from across the market. We offer both first and second charge mortgages, but not deals that you can only obtain by going direct to a lender.
We also take care of all the administration for mortgages and life cover applications as well as liaise with Hampshire estate agents, mortgage lenders and Hampshire solicitors to make sure the process is as smooth and hassle-free for you as possible.

Fee free on over 90% of the mortgages we arrange. There is a £299 fee on mortgages under £100,000, and complex or adverse credit cases can carry a fee of up to £995, agreed in writing before we start.
Typically fee-free for standard residential mortgages, our commission is paid by the lender on completion. Fees may apply for complex or specialist cases, always disclosed upfront in writing.
Shirley, Portswood, Bassett, Bitterne, Woolston, Sholing, Ocean Village and the city centre, plus Totton and Hedge End. Our office is in Romsey, about 15 to 20 minutes away.
First time buyers, home movers, remortgages, buy to let (including portfolio landlords).
Speak to a qualified adviser today, we offer flexible appointments including evenings and weekends.
Our Southampton mortgage advisers bring over 20 years of combined experience in residential and buy to let lending. We provide whole of market mortgage advice, comparing high street banks, building societies and specialist lenders to find mortgage products that suit your circumstances and the criteria you need to meet.
We support first time buyers, home movers, remortgages, buy to let investors and clients with complex incomes across the city, from Portswood and Ocean Village to Shirley, Bitterne and Bassett. We also advise on life insurance, critical illness cover and income protection.

Southampton is 15 to 20 minutes from our office in Romsey, so a lot of the people we help live in the city or are trying to buy here. These are straight answers to the questions our mortgage advisers hear most, plus the local details that can change the outcome.

Where people are buying in Southampton
Shirley and Freemantle are full of Victorian and Edwardian terraces, and that is where a lot of our first time buyers get onto the property ladder. Portswood and Highfield sit by the university, with family homes on one street and student lets on the next. Bassett, up towards the Common, is leafier and pricier, with bigger semis and detached houses.
Across the Itchen, Bitterne, Woolston and Sholing usually give you more house for the money, and Woolston has changed a lot since Centenary Quay went up on the old shipyard site. Ocean Village and the city centre are mostly flats, from conversions near the Old Town walls to newer blocks by the water. Just outside the city, Totton and Hedge End are popular with families who want a garden and quick access to the M27.
Older terraces can come back from the valuation with damp or a loft conversion with no building regulations sign off. Knowing which lenders are relaxed about which issue saves a wasted application.
First time buyers: a worked example
The ONS puts the average price paid by first time buyers in Southampton at £210,000 (UK House Price Index, July 2026, provisional). With a 10% deposit of £21,000, you would need a mortgage of £189,000. Plenty of lenders cap borrowing at around 4.5 times income, so you would typically need a household income of about £42,000.
On a repayment mortgage over 30 years, an illustrative rate of 4.5% works out at about £958 a month. At 5% it is about £1,015. Stretch the term to 35 years at 4.5% and it drops to around £894, but you pay more interest overall. These are examples, not quotes.
Stamp duty on that purchase would be £0, because first time buyers in England pay nothing on the first £300,000. Check your own figures with our stamp duty calculator, and our first time buyer mortgages guide walks you through the rest.
Buying with a 5% deposit
You can still buy here with 5% down. On the same £210,000 home that is a £10,500 deposit and a £199,500 mortgage, or roughly £1,011 a month over 30 years at 4.5%, again purely as an illustration.
The catch is choice. Fewer lenders go to 95%, the rates are higher, and new build flats are often capped at a lower loan to value. Our 5% deposit mortgages page explains how to give yourself the best chance.
Working at the port, the university or the hospital
Lots of our clients work for the city's big employers: the port and the cruise lines, the University of Southampton and Solent University, and University Hospital Southampton. Port and shift workers often rely on overtime and allowances, university staff are sometimes on fixed term contracts, hospital staff have bank shifts and unsocial hours pay, and plenty of contractors working for them are self employed.
Lenders treat that income very differently. Some use all of your regular overtime and others only half, which on £8,000 a year can mean around £18,000 of borrowing either way. NHS staff may find our NHS mortgages page useful.
City centre flats, high rise blocks and new builds
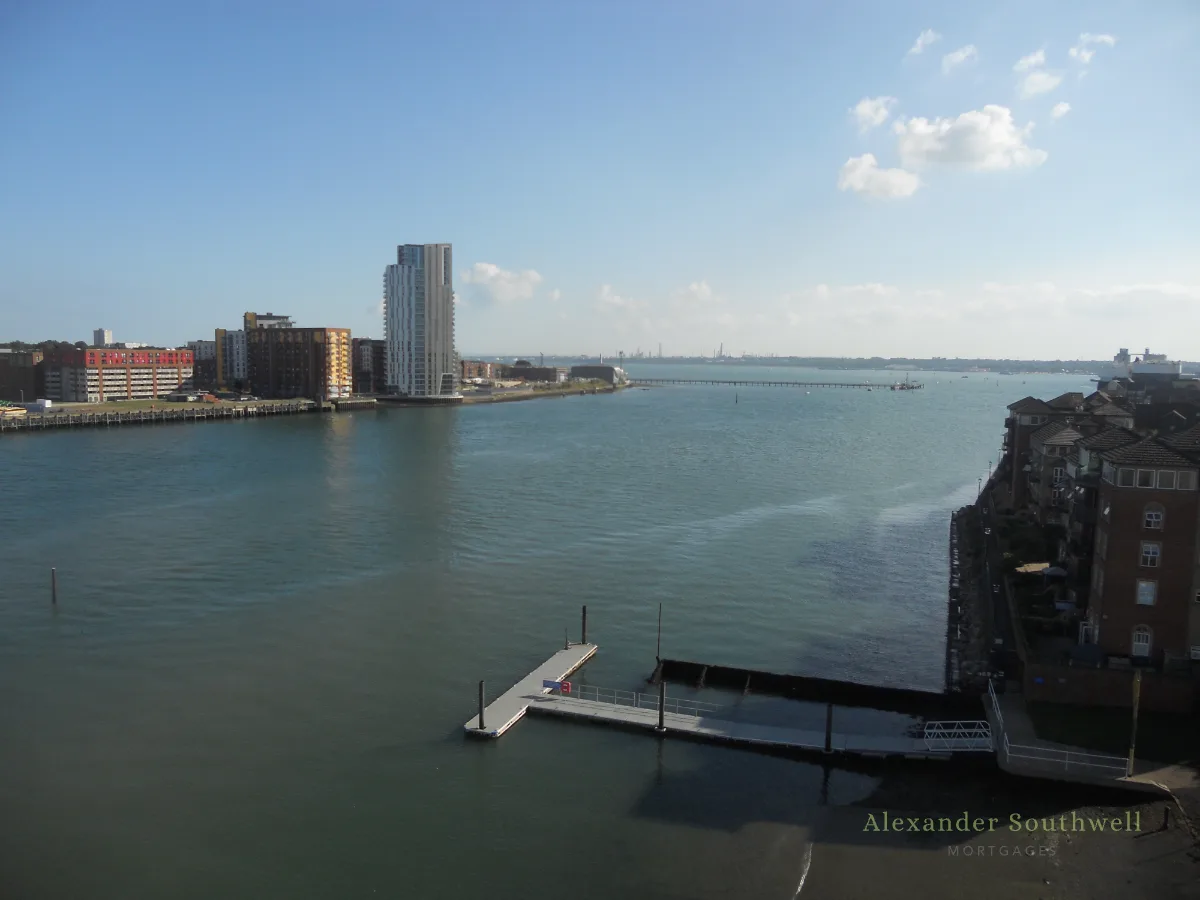
Flats are the cheapest way into the city, at an average of £153,000 according to the ONS, but this is also where lender criteria bite hardest. Some lenders are cautious about blocks above a certain number of storeys, very small flats (many want at least 30 square metres or so), flats above shops or bars, and short leases. A taller block may need an EWS1 form on the cladding, and some lenders count the service charge in affordability. None of that rules you out. It just means picking the lender to suit the building.
New builds have their own rules too. Offers can run out before the build is finished, any developer incentive has to be declared, and some lenders lend less on new build flats. Read our new build mortgages guide before you pay a reservation fee, not after.
Buy to let and student lets
The ONS puts the average private rent in Southampton at £1,257 a month (August 2026), up 3.4% in a year. With two universities, student houses in Portswood, Highfield, Swaythling and Bevois Valley are a big part of the local rental market, and buy to let mortgages on them need more thought than most.
Shared houses need care. You usually need planning permission to turn a family home into a small HMO here, and in wards including Portswood, Bevois, Bassett, Swaythling and Freemantle smaller shared houses need a council licence too. Lenders typically want the rental income to cover the payment by 125% to 145% at a stressed rate. We arrange buy to let mortgages and HMO mortgages, including limited company purchases. Most buy to let mortgages are not regulated by the FCA.
Commuting, remortgaging and moving
Southampton Central has direct trains to London Waterloo, with the quicker services taking around 80 minutes, and Southampton Airport Parkway is on the same line. The M27 and M3 are right on the doorstep.
If your fixed rate ends in the next six months, talk to us now. Your lender's product transfer is sometimes the right answer, but we compare it with the market first. Moving up from a Shirley terrace to a semi in Bassett or out to Hedge End? Our remortgage advice and moving home mortgages pages cover both.
Checking who you are dealing with
Any mortgage adviser you use in Southampton should be on the FCA register. It shows whether a firm is directly authorised or an appointed representative of a network, and what it is allowed to do. Our firm reference number is 1011890.
It is fair to ask how a broker gets paid. We are fee free on over 90% of cases, because the lender pays us. There is a £299 fee on mortgages under £100,000, and complex or adverse credit cases can carry a fee of up to £995, always agreed in writing before any work starts. You can see what other clients say on our reviews page, and we also help buyers in nearby Eastleigh, Romsey and the New Forest.
How far is your office from Southampton?
Our office is at NIX Business Centre in Romsey, about 15 to 20 minutes' drive from the city centre. Plenty of clients never visit and do everything by phone, video call and WhatsApp.
How much can I borrow on my salary?
Most lenders work on around 4 to 4.5 times income, and some go to 5 times or a little more for higher earners or certain professions. The calculator below gives a quick guide, and an Agreement in Principle firms it up.
How long does getting a mortgage take?
An Agreement in Principle can often be done the same day. Application to mortgage offer usually takes two to four weeks, and the whole purchase is more often 12 to 16 weeks.
What if I have had credit problems?
Missed payments, defaults or a CCJ do not automatically rule you out, but they shorten the list of lenders. The first job is to see your credit file the way lenders see it. Our Check My File guide explains how.
Can family help with my deposit?
Yes. Most lenders accept a gifted deposit from family, with a signed gift letter and proof of where the money came from. Some families help in other ways, such as a guarantor mortgage or a joint borrower sole proprietor mortgage.
Want to know where you stand? Call us on 03300 432 428 for fee free mortgage advice in Southampton, or have a play with our mortgage calculators first.
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
From your initial consultation to when your mortgage completes we manage the whole mortgage process for you. We coordinate with estate agents and solicitors where necessary to keep everyone moving towards your completion date.
A free, no obligation phone or video call to discuss your goals, deposit, income, credit history and the Southampton or Hampshire area you’re buying in. This gives us everything we need to start looking at your options.
Your adviser will compare mortgage products across suitable lenders and prepare a tailored recommendation. You’ll receive an Illustration (ESIS) showing the interest rate, fees and total cost over the mortgage term so you can make an informed decision.
We can often get a Decision in Principle (DIP) the same day or within 24 hours. This is essential when making offers on houses in popular Southampton areas like Freemantle, Bitterne Park or Ocean Village where competition can be fierce.
We’ll handle the paperwork, submit your documents to the lender, liaise on your behalf and arrange the valuation or survey. You won’t need to chase. We do that for you.
We’ll track your case through underwriting, chase solicitors and other parties if needed and keep you updated through to exchange and completion. Once you’ve got your keys we’ll diarise a review before any fixed rate ends so you’re never left on an expensive standard variable rate.
Being prepared with the right paperwork
Documents You’ll Need
Southampton is still one of the better value places to buy in this part of Hampshire. The ONS puts the average price at £236,000 in July 2026 (provisional), up 2.4% on a year earlier, and the waterfront and Woolston keep adding new homes.
Waterfront and city centre regeneration, plus Centenary Quay in Woolston, keeps adding new homes, many of them flats.
Detached £419,000, semi detached £314,000, terraced £252,000 and flats £153,000 in July 2026. First time buyers paid an average of £210,000 (ONS UK House Price Index).
Demand comes from first time buyers, students and university staff, port and hospital workers, and families looking at Bassett, Highfield and Bitterne Park.
Southampton Central and Southampton Airport Parkway have direct trains to London Waterloo, and the M27 and M3 are on the doorstep.

Buying your first home is a big step, and we take the hard work off your plate. We work out what you can borrow, compare mortgage products across different lenders, explain the deposit and costs, and check whether a scheme such as shared ownership could help. We are with you every step of the way, from the first call to getting your keys.
Learn more about first-time buyer mortgages →Most Southampton homeowners remortgage when their deal ends, to keep their monthly repayments down and avoid the standard variable rate. Others want to release equity for home improvements, buy out a partner or raise a deposit for a buy to let. We compare your lender's offer with the wider mortgage market and handle the paperwork for you.
Learn more about remortgage advice →Buy to let mortgages are assessed on rental income as much as on your own earnings, and the rules on tax and landlord responsibilities keep changing. We advise first time landlords, portfolio landlords and limited company buyers, including HMOs and student lets.
Learn more about buy-to-let mortgages →New builds usually come with a 10 year warranty and no chain, but they have their own quirks. Lenders may want a bigger deposit on new build flats, your mortgage offer has to last until the build is finished, and any incentives must be declared. We know which lenders suit which developments.
Learn more about new build mortgages →Alexander Southwell Mortgage Services is a local mortgage broker established to make expert mortgage advice accessible without the fees, and we have grown through recommendations from happy clients across the south coast. Unlike a bank or a tied financial adviser, we work for you, not a lender.
We are directly authorised and regulated by the Financial Conduct Authority (number 1011890), not an appointed representative of a larger network, so the advice you receive is our own.
We are a small, friendly team. We explain things clearly, keep in touch by phone, WhatsApp and email, and chase every part of your mortgage application so you do not have to. It is the reason 193 clients have given us five stars on Google.
Your home may be repossessed if you do not keep up repayments on your mortgage.
.webp)
Yes. Alexander Southwell Mortgage Services is based in Romsey, about 15 to 20 minutes from Southampton, and we cover the whole city. We are fee free on over 90% of cases because the lender pays us. There is a £299 fee on mortgages under £100,000, and complex or adverse cases can carry a fee of up to £995, always agreed with you in writing first.
Most lenders need at least a 5% deposit. With the average Southampton first time buyer price at £210,000 (ONS, July 2026), that is £10,500. Putting down 10% (£21,000) usually opens up more lenders and better rates, and first time buyers pay no stamp duty on homes up to £300,000.
Yes. Most lenders want two years of accounts or SA302 tax calculations with matching tax year overviews, and some will look at one year. How your income is worked out (salary and dividends, net profit or day rate) makes a big difference to what you can borrow, so it pays to pick the lender carefully.
An Agreement in Principle (also called a Decision in Principle or Mortgage in Principle) is a lender's written indication of how much it would be prepared to lend you, based on a credit check and your basic details. Most Southampton estate agents will want to see one before they put your offer forward, and we can often arrange it the same day.
A bank can only offer you its own products, while a whole of market broker compares deals from dozens of lenders, including building societies and specialist lenders. Going direct can mean missing a more suitable rate or a lender whose criteria better fit your personal circumstances. We give advice based on the whole of market and manage the application for you from start to finish.