Being prepared with the right documentsDocuments You’ll Need
Finding a mortgage can be overwhelming, especially when you’re juggling property searches, solicitors and other buyers.
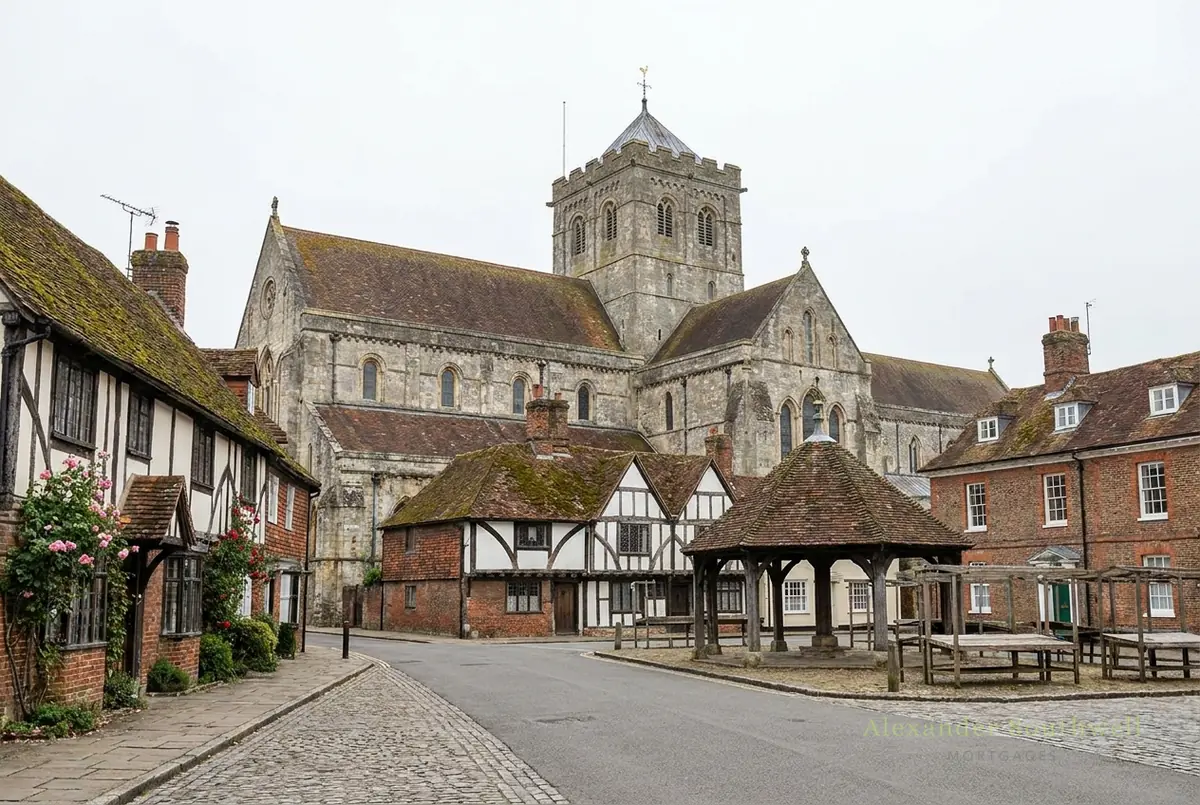
Romsey is a charming historic market town, known for its beautiful abbey, the River Test, and excellent links to Southampton and Salisbury. It's a popular choice for families and commuters alike, with a mix of period properties, modern developments, and a strong sense of community.


Alexander Southwell Mortgage Services Ltd offer a comprehensive range of mortgage products from across the market. We offer both first and second charge mortgages, but not deals that you can only obtain by going direct to a lender.
We work closely with Romsey estate agents, solicitors, and surveyors to make sure your mortgage completes as smoothly as possible.

Low-Cost Specialist Advice: Fee-free options available for clean credit and £100k+ loans.
Typically fee-free for standard residential mortgages, our commission is paid by the lender on completion. Fees may apply for complex or specialist cases, always disclosed upfront in writing.
Covering Romsey (SO51), Chandler's Ford, Eastleigh, Totton, Ampfield, Braishfield, North Baddesley, Michelmersh, Timsbury, and surrounding Test Valley villages across Hampshire.
First time buyers, home movers, remortgages, buy to let (including portfolio landlords).
Speak to a qualified adviser today. We offer flexible appointments including evenings and weekends.
Our advisers have helped hundreds of clients across Romsey (SO51), Chandler's Ford, Ampfield, Braishfield, Michelmersh, North Baddesley, Timsbury, Lockerley, Awbridge, Wellow, Mottisfont, and the surrounding villages secure the right mortgage. Whether you're a first-time buyer, home mover, or landlord, we're here to help.

From your initial consultation to when your mortgage completes we manage the whole process for you. We coordinate with estate agents and solicitors where necessary to keep everyone moving towards your completion date.
Call or enquire online and one of our Romsey mortgage advisers will get back to you quickly to discuss your needs.
Your adviser will compare mortgage products across suitable lenders and prepare a tailored recommendation. You’ll receive an Illustration (ESIS) showing the interest rate, fees and total cost over the mortgage term so you can make an informed decision.
We'll secure a Decision in Principle (DIP) so you can make offers on Romsey properties with confidence.
We’ll handle the admin, submit your documents to the lender, liaise on your behalf and arrange the valuation or survey. You won’t need to chase. We do that for you.
We’ll track your case through underwriting, chase solicitors and other parties if needed and keep you updated through to exchange and completion. Once you’ve got your keys we’ll diarise a review before any fixed rate ends so you’re never left on an expensive standard variable rate.
Being prepared with the right documentsDocuments You’ll Need
Romsey is one of Hampshire's most desirable market towns, consistently attracting buyers who want village-style living with easy access to Winchester and Salisbury. Property prices tend to be higher than neighbouring towns, reflecting strong demand and limited stock. Detached family homes and period cottages are particularly sought after.
Romsey is a small market town with a tightly held supply of period and village property, so well presented homes tend to sell quickly.
ONS figures put the average house price in Test Valley at £368,000 in July 2026 (provisional), roughly level with a year earlier. First time buyers paid £283,000 on average.
Demand comes from families moving out of Southampton, professionals commuting to the M3 and M27, and downsizers who want a walkable high street. If you would rather buy in the city itself, the same team works as a mortgage broker in Southampton too.
The A3057 and A27 link Romsey to Winchester and the coast, with the M3 and M27 close by and mainline rail a short drive away.
Getting a new mortgage is one of the biggest financial decisions most of us ever make. Our team of expert mortgage advisors is here to guide you through the whole process, from your initial consultation to the day you complete, with clear, jargon free advice at every step.
Because we do not charge fees for standard residential mortgage advice, you get the same whole of market expertise other brokers offer, without the cost. Everything we recommend is designed around your financial situation, your long term goals and your personal circumstances.
We compare mortgage products from high street banks, building societies and specialist lenders across the UK mortgage market. That depth of access means we can match your circumstances to the right mortgage deal rather than a limited panel.
Whether you need a simple purchase mortgage or something more complex, we search the options and explain every recommendation clearly so you can make an informed decision.
Once you are ready to proceed, we manage the whole mortgage application on your behalf. We submit your documents, liaise with the lender, chase solicitors where needed and keep you informed from start to finish.
Our aim is a smooth, stress free application process, with ongoing support that continues after completion, including a review before any fixed rate ends.
Self employed borrowers, contractors and limited company directors often face extra questions about income and accounts. We know which mortgage lenders take a flexible view and how to present your financial situation in the best light.
We will assess your unique circumstances, explain what different lenders need and focus on the products that suit the way you earn.
Buying your first property is exciting, but it can feel daunting too. We help first time buyers work out what they can afford to borrow, understand shared ownership and low deposit schemes, and turn the dream of a first home into reality.
From your first enquiry to getting the keys, we handle the hard work and explain every step, giving you the confidence to proceed.
When your current deal ends, switching to a different lender could save money every month. We compare your options, manage the switch and keep remortgaging simple.
If you are moving home or have bad credit on your file, we work with specialist lenders who look beyond the credit score, catering for circumstances other advisers might turn away.
Many other brokers charge fees of several hundred pounds for the same work. We are typically fee free, paid by the lender on completion, and our customers consistently describe an excellent service from a friendly, experienced team that goes the extra mile.
We are an independent company and we treat every mortgage as if it were our own. Absolutely no pressure, no jargon and no hidden costs, just expert advice you can trust.
Our office sits just outside the heart of Romsey, easily accessible whether you are popping in after a coffee at one of the town's independent shops and cafes or travelling in from the surrounding villages. Commuters across the south coast can book phone or video appointments in the evening or at the weekend, so getting expert mortgage advice fits around your working week.
Ready to talk? Get in touch for a free initial consultation with no obligation. Call 03300 432 428, email enquiries@as-mortgages.co.uk or book an appointment online, and one of our team will be glad to help.
Your home may be repossessed if you do not keep up repayments on your mortgage.
A lot of what comes up when you search for Romsey mortgage brokers is directory listings and national firms. We are a small, independent mortgage broker with an office in the town itself, and you are welcome to come in and see us. Here is the practical stuff, plus the local details that can change which lender says yes.

Finding us, and meeting in person
We are at NIX Business Centre, 2 Park Court, on the Abbey Park Industrial Centre, Romsey SO51 9DH. That is on the south east side of town, a short drive from the town centre, and junction 3 of the M27 is about three miles away. It is a shared office building, so let us know when you book and we will tell you where to park and come and meet you.
Some people like to come in for the first chat with their payslips. Others never visit and do it all by phone, video call and WhatsApp, often in the evening. Both work fine. You get the same mortgage advisor from start to finish either way, not a different person every time you ring.
What buying in Romsey costs: a worked example
The ONS puts the average house price in Test Valley at £368,000 in July 2026 (provisional), roughly level with a year earlier. By type it was £602,000 for a detached house, £357,000 for a semi, £283,000 for a terrace and £170,000 for a flat. Romsey itself usually sits above that.
Take a first time buyer paying the Test Valley first time buyer average of £283,000 with a 10% deposit of £28,300. That leaves a mortgage of £254,700. Lots of lenders cap mortgage borrowing at around 4.5 times income, so you would typically need a household income of about £56,600. Some lenders go higher for bigger earners, which is where shopping the whole mortgage market pays off.
On a repayment mortgage over 30 years, an illustrative rate of 4.5% works out at about £1,291 a month. At 5% it is about £1,367. Stretch it to 35 years at 4.5% and it drops to around £1,205, but you pay more interest over the life of the loan. These are examples, not quotes. Stamp duty would be £0, because first time buyers in England pay nothing on the first £300,000. Run your own numbers on our stamp duty calculator, and our first time buyer mortgages guide covers the rest.
Where people are buying
The town centre is all period stuff: Georgian fronts on The Hundred, cottages off Church Street and Middlebridge Street, and terraces that have been knocked about over the years. Lovely, but older homes can come back from the valuation with damp or an extension nobody signed off.
Further out, Cupernham and the old Romsey Extra parish have lots of family semis, and North Baddesley, Nursling and Rownhams are popular with people who work in Southampton. Ampfield and Braishfield are pricier village living.
New build at Abbotswood and Whitenap
Abbotswood, on the northern edge of town, has added around 800 homes, and Whitenap to the south is planned for about 1,300 more. That is a lot of new build in one small town.
New builds have their own rules. Some lenders lend less on new build flats, offers can expire before the house is finished, and every developer incentive has to be declared to the lender. Read our new build mortgages page before you pay a reservation fee, not after.
Commuting from Romsey
Romsey station has direct trains to Southampton Central and to Salisbury, both usually around 20 minutes. Winchester is roughly half an hour by car, and the M27 and M3 put Portsmouth, Basingstoke and London in reach for people who only go into the office a couple of days a week.
Lenders look at your actual outgoings, so a season ticket or a long daily drive does count against affordability. It is worth building that into your budget before you fall for a house in Wellow or Lockerley.
Self employed and contractors
Plenty of Romsey people work for themselves. Most lenders want two years of accounts or SA302s, though some will look at one.
How your income is worked out (net profit, salary plus dividends, or a day rate) can change what you can borrow by tens of thousands. Our contractor mortgages page explains how day rate lending works.
Remortgaging, moving and buy to let
If your fixed rate ends in the next six months, talk to us now. Your lender will usually offer you a product transfer, and sometimes that is the right answer. We compare it with the market and time the switch so you do not slip onto the standard variable rate. Our remortgage and moving home pages have more.
We also arrange buy to let mortgages for first time and portfolio landlords. Most buy to let mortgages are not regulated by the FCA.
Protecting the home once you have it
You will need buildings insurance in place for completion. Life insurance and income protection deserve a proper look too, especially if one salary pays most of the mortgage.
We can go through mortgage protection alongside the mortgage, in plain English and with no pressure to take anything.
Can I meet a mortgage advisor in person in Romsey?
Yes. Our office is at NIX Business Centre on the Abbey Park Industrial Centre, Romsey SO51 9DH. Book a time and we will meet you there, or we can do the whole thing by phone or video call if that is easier.
Is it better to go to my bank or a mortgage broker?
Your bank can only offer its own deals. As an independent mortgage broker we compare high street banks, building societies and specialist lenders, which matters most if your income or credit history is anything other than simple. The aim is the right mortgage for you, not just the best deal on paper.
How much can I borrow on my salary?
Most lenders work on around 4 to 4.5 times income, and some go to 5 times or a little more for higher earners. The calculator below gives a quick guide, and an Agreement in Principle firms it up.
How long does the mortgage process take?
An Agreement in Principle can often be done the same day. Application to mortgage offer usually takes two to four weeks, and the whole purchase more often takes 12 to 16 weeks.
What if I have had credit problems?
Missed payments, defaults or a CCJ do not automatically rule you out, but they shorten the list of lenders. The first job is to see your credit file the way lenders see it. Our Check My File guide explains how.
Next steps are easy. Call us on 03300 432 428, pop into the office by appointment, or have a play with our mortgage calculators first.
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
Buying your first home in Romsey is an exciting step. Our advisers will help you understand your budget, navigate available government schemes, and find a mortgage that works for you, guiding you from your first enquiry right through to getting the keys.
Learn more about first-time buyer mortgages →Whether your current deal is ending or you want to release equity from your Romsey home, our advisers will search across the whole market to find you a better rate. We take care of the paperwork, making the process as straightforward as possible.
Learn more about remortgage advice →Romsey has a steady rental market, particularly appealing to professional tenants who want a quieter lifestyle within easy commuting distance of Southampton. Our advisers specialise in buy-to-let mortgages and can help you build or expand your property portfolio in the Test Valley area.
Learn more about buy-to-let mortgages →There are a number of new build developments around Romsey and the surrounding area. New build mortgages have specific requirements, and our advisers are experienced in securing the right deal, including working with developers to meet reservation deadlines.
Learn more about new build mortgages →.webp)
Yes, and we are based right here in Romsey, at NIX Business Centre, 2 Park Court, SO51 9DH. We are fee free on over 90% of cases because the lender pays us a commission when your mortgage completes. There is a £299 fee on mortgages under £100,000, and complex or adverse credit cases can carry a fee of up to £995, always agreed with you in writing first.
Most lenders need at least a 5% deposit. First time buyers in Test Valley paid £283,000 on average in July 2026 (ONS, provisional), so 5% of that is about £14,150. Putting down 10% or more opens up more lenders and usually better rates.
Yes. We help many self-employed buyers and remortgagors across Romsey and the Test Valley area. Most lenders need two years of accounts or SA302 tax calculations, though some specialist lenders will consider one year. As a whole-of-market broker we can find the right option for your situation.
An Agreement in Principle (AIP) confirms in writing how much a lender is willing to lend you. Romsey estate agents and sellers will typically want to see one before accepting your offer. Because we are based locally we can arrange your AIP quickly, often on the same day you get in touch.