Being prepared with the right paperwork
Documents You’ll Need
Finding a mortgage can be overwhelming, especially when you’re juggling property searches, solicitors and other buyers.
A mortgage broker in Brighton gives you access to lenders right across the market, so you can get a great deal without the stress of approaching banks individually. Brighton's vibrant property market attracts buyers from all walks of life, so having an experienced adviser really does help.


Alexander Southwell Mortgage Services Ltd offer a comprehensive range of mortgage products from across the market. We offer both first and second charge mortgages, but not deals that you can only obtain by going direct to a lender.
We also take care of all the administration for mortgages and life cover applications, as well as liaising with Brighton estate agents, mortgage lenders and solicitors to make the whole process as smooth and stress-free as possible.

Low-Cost Specialist Advice: Fee-free options available for clean credit and £100k+ loans.
Typically fee-free for standard residential mortgages, our commission is paid by the lender on completion. Fees may apply for complex or specialist cases, always disclosed upfront in writing.
Based in Romsey, Hampshire, with full remote coverage across Brighton, Hove and the wider East Sussex area via phone and video appointments.
First time buyers, home movers, remortgages, buy to let (including portfolio landlords).
Speak to a qualified adviser today: we offer flexible appointments including evenings and weekends.
Our Brighton mortgage advisers have over 20 years of experience in residential and buy to let lending. We offer whole-of-market access to high-street banks, building societies and specialist lenders, supporting first time buyers, home movers, remortgages, buy to let investors and clients with complex incomes across Kemptown, Hove, Preston Park, Fiveways, Portslade and beyond. We also advise on life insurance, critical illness cover and income protection to protect your Brighton property purchase.

From your initial consultation to when your mortgage completes we manage the whole process for you. We coordinate with estate agents and solicitors where necessary to keep everyone moving towards your completion date.
A free, no obligation phone or video call to discuss your goals, deposit, income, credit history and the area of Brighton or Hove you are looking to buy in. This gives us everything we need to start searching for the right mortgage for you.
Your adviser will compare mortgage products across suitable lenders and prepare a tailored recommendation. You’ll receive an Illustration (ESIS) showing the interest rate, fees and total cost over the mortgage term so you can make an informed decision.
We can often get a Decision in Principle the same day or within 24 hours. This is especially useful in Brighton where sought-after properties in areas like Kemptown, Seven Dials and Hove can attract multiple offers very quickly.
We’ll handle the paperwork, submit your documents to the lender, liaise on your behalf and arrange the valuation or survey. You won’t need to chase: we do that for you.
We’ll track your case through underwriting, chase solicitors and other parties if needed and keep you updated through to exchange and completion. Once you’ve got your keys we’ll diarise a review before any fixed rate ends so you’re never left on an expensive standard variable rate.
Being prepared with the right paperwork
Documents You’ll Need
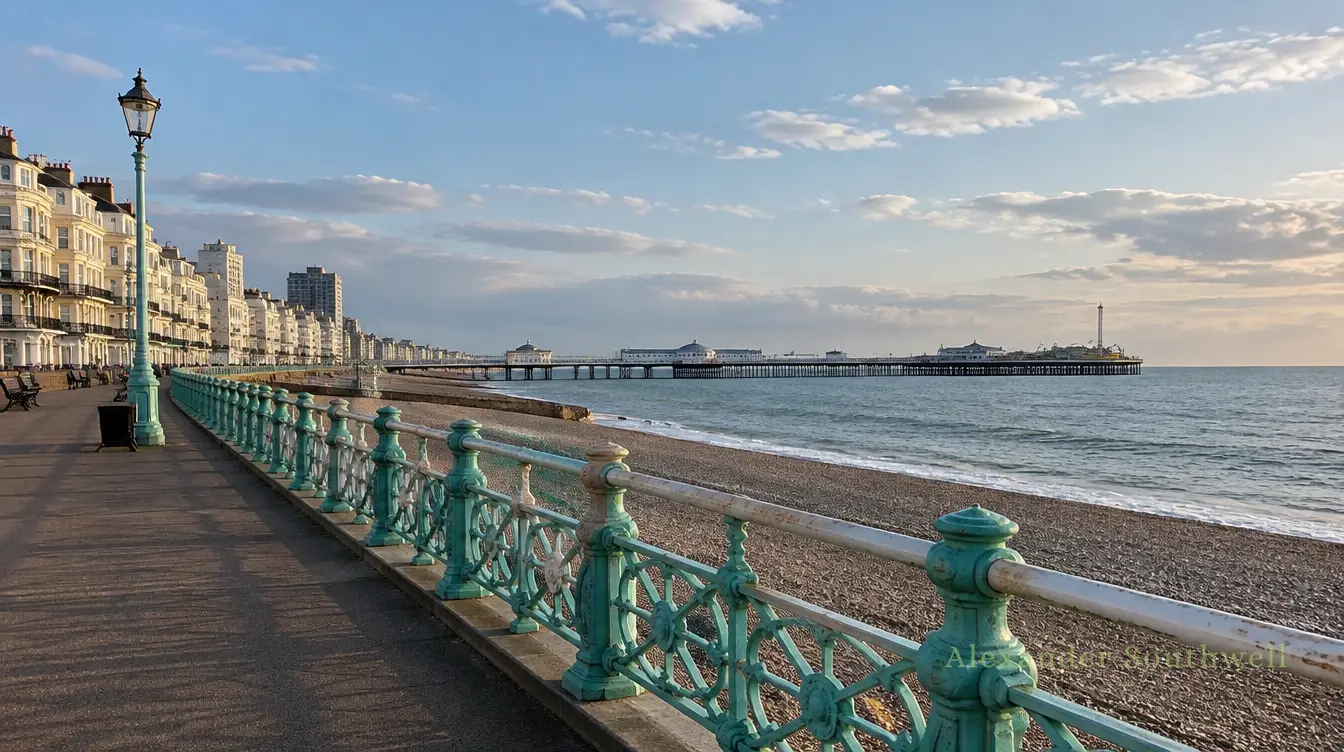
Brighton is one of the UK's most popular coastal cities, attracting a real mix of buyers from young professionals and families to retirees and investors. Understanding the local market helps us give you the best possible mortgage advice.
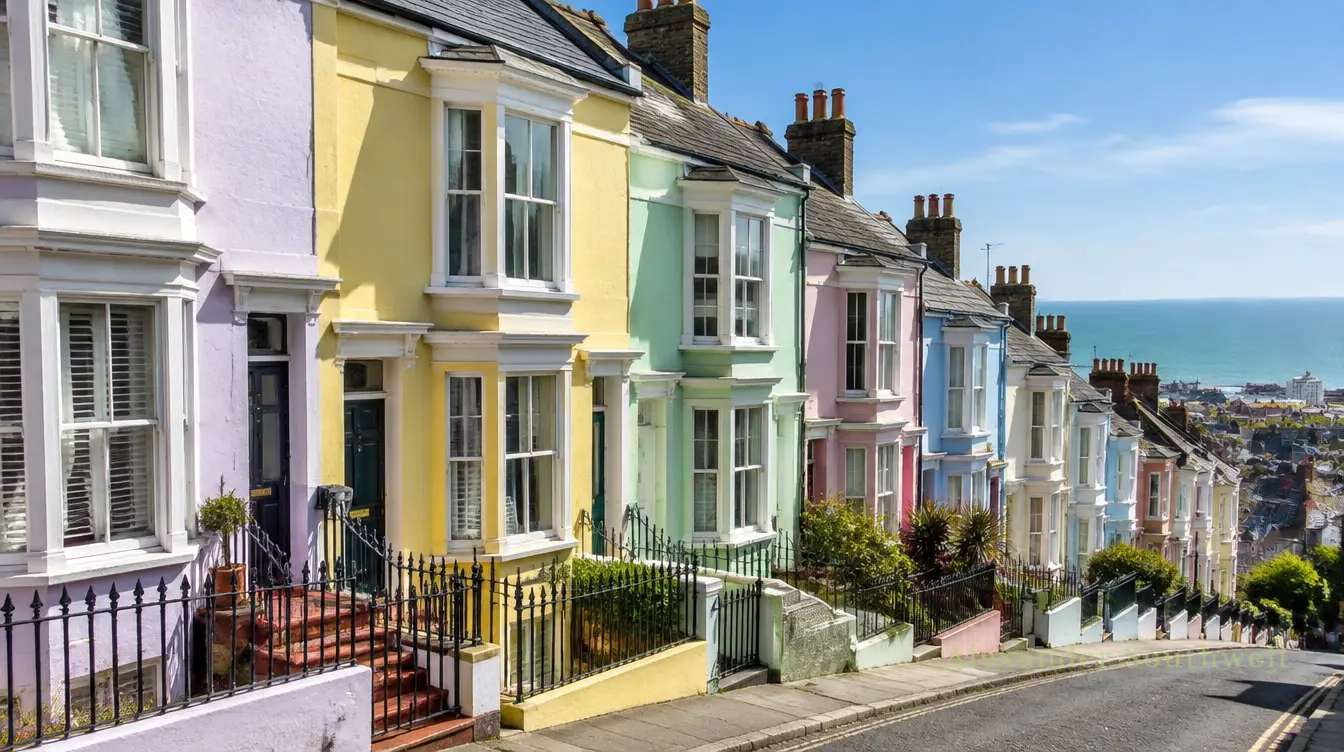
The Brighton and Hove area offers everything from Victorian terraces and Regency seafront apartments to modern new build developments, giving buyers a wide range of choices at various price points.
Average house prices in Brighton sit broadly between £350,000 and £450,000, though this varies significantly between central streets, seafront properties and the more affordable outskirts of the city.
Demand is driven by London commuters on the fast Victoria and London Bridge services, young professionals attracted by Brighton's culture and tech scene, and retirees seeking a vibrant coastal lifestyle.
The fast train from Brighton to London Victoria takes around 52 minutes, making it one of the most popular commuter towns in the south east and keeping property demand consistently strong.
.webp)
Buying your first home in Brighton is a big moment, and we love helping local people make it happen. The market moves quickly here, so we'll work out exactly what you can borrow, explain the deposit you'll need and every cost along the way, and get your Agreement in Principle sorted before you start viewing. We'll also tell you about any schemes that could help, including shared ownership on developments across Brighton and Hove. No jargon, just straight answers.
Most Brighton homeowners remortgage when their current deal comes to an end, to lock in a new rate before they roll onto their lender's standard variable rate. We can secure a new deal up to six months early. If you want to raise money for home improvements, help a family member onto the ladder or put down a deposit on a buy to let, we'll look at releasing equity too. We search the whole market and handle the full application, so the switch is as smooth as possible.
Whether you're buying your first investment property, letting your current home and moving on, or growing a portfolio, we can find you the right deal. Brighton's rental market is strong, driven by two universities, a big community of young professionals and London commuters. We advise on personal and limited company buy to let, HMOs and portfolio lending, and we'll check the rent works against lenders' stress tests before you commit.
New build homes can be a great choice for first time buyers, downsizers and landlords: no chain, lower running costs and usually a 10 year warranty. They do have their quirks though. Some lenders want a bigger deposit, exchange deadlines come round fast, and your mortgage offer has to line up with the build completion date. We know which lenders are comfortable with new builds and we'll manage the whole thing from reservation to picking up your keys.
Brighton and Hove isn't a cheap place to buy. The average home sold for around £409,000 in July 2026 (UK House Price Index), with prices down 1.1% on the year, which takes a little heat out of the market but doesn't change the big picture. Add in Regency conversions, basement flats, short leases and homes right on the seafront, and lender choice matters more here than almost anywhere. Good mortgage advice means knowing which mortgage providers will be comfortable with the property and your financial situation before you apply.
We start with your personal circumstances and financial goals: what you earn, what you've saved, how long you plan to stay and what monthly payment feels comfortable. Then we compare mortgage deals across the whole market, not a single lender, and explain in plain English why we think one is the right deal for you.
First time buyers paid around £344,000 on average in July 2026. That usually means a flat in Kemptown, Hanover or Preston Park, or a house further out in Moulsecoomb, Portslade or Patcham. We'll show you what you can borrow, which lenders accept gifted deposits and how to make your offer stand out to estate agents.
A lot of Brighton homes are converted flats with a share of freehold, a short lease or a flying freehold. Some lenders are fine with these and some aren't. We check the details early so your mortgage application doesn't stall at valuation, and we'll flag anything your solicitor needs to look at.
Brighton has a huge creative and freelance community, plus plenty of people running their own businesses. If your income doesn't fit a payslip, or there's a blip in your credit history, we know the specialist lenders who'll look at the full picture rather than ticking boxes.
Home movers trading up to Hove, Fiveways or Withdean need the sums to work on both sides of the move. We'll look at porting your mortgage, early repayment charges and extra borrowing. If you're staying put, we'll compare your lender's offer with the rest of the market well before your deal ends.
With trains to London in around an hour, plenty of our clients earn London salaries and live by the sea. Landlords like the city too: average rents were around £1,808 a month in August 2026 (ONS). We'll check bonuses and commission count towards your borrowing, and that rents pass lenders' tests on any buy to let.
We're authorised and regulated by the Financial Conduct Authority (FCA 1011890). We'll submit applications, deal with the lender, solicitor and estate agent, and look after the entire process, including protection advice and home insurance so your new home is covered from day one. Over 90% of our cases are fee free, and that's how we've earned 193 five star Google reviews.
Your home may be repossessed if you do not keep up repayments on your mortgage.
.webp)
Yes. We give whole of market mortgage advice to buyers across Brighton, Hove and East Sussex, and over 90% of our cases are fee free because the lender pays us when your mortgage completes. Mortgages under £100,000 carry a £299 fee, and complex or adverse credit cases can carry a fee of up to £995, always agreed with you in writing first.
Most lenders want at least 5%. First time buyers in Brighton and Hove paid around £344,000 on average in July 2026 (UK House Price Index), so 5% is about £17,200 and 10% about £34,400. A 10 to 15% deposit opens up more lenders and better rates, which makes a real difference in a city where prices are well above the national average.
Yes. Many lenders are happy to lend to self-employed applicants in Brighton, provided you can supply two years of accounts or SA302 tax calculations. Some specialist lenders accept one year of trading. Brighton has a thriving freelance and creative economy, and we work with lenders experienced in non-standard income structures.
An Agreement in Principle (also called a Decision in Principle or Mortgage in Principle) is a written confirmation from a lender of how much they are prepared to lend. Most Brighton estate agents will ask to see one before accepting an offer. We can arrange yours quickly, usually within 24 hours.